By Phapano Phasha
Just before the 18th BRICS Summit convenes in New Delhi, India, on 12–13 September 2026, a wave of cross-border capital has swept into India’s financial sector.
According to a Reuters report published on August 13, foreign investments into Indian banking, non-banking finance, insurance, and financial technology surged to about US$11.7 billion in 2025, with an additional $1.4bn recorded in the first half of 2026.
The deal sheet is striking. Japan's Mitsubishi UFJ Financial Group took a 20 percent stake in the non-bank lender Shriram Finance for roughly 4.4 billion US dollars. The United Arab Emirates' (UAE's) NBD, which is one of the largest banking groups in the Middle East, acquired a controlling 60% stake in RBL Bank, a private commercial bank based in Mumbai, for approximately 3 billion US dollars.
Bank of America Corporation plans a near 50 percent investment in the lending arm of Jio Financial Services, a core investment company registered with the Reserve Bank of India. Meta Platforms injected $900 million into the financial technology firm CRED, which operates a membership-based credit card payment platform.
The Blackstone Group, Bain Capital, and Abu Dhabi's International Holding Company have also invested.
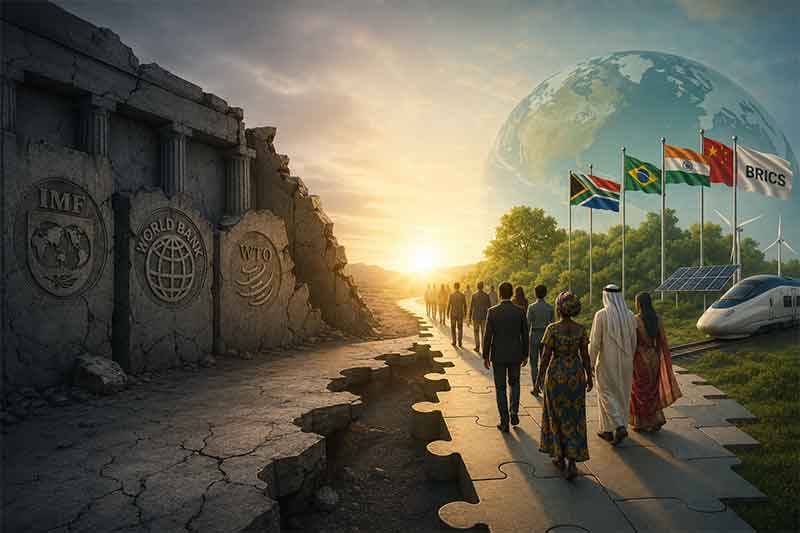
India assumed the BRICS chairmanship on 1 January 2026 under the theme Building for Resilience, Innovation, Cooperation and Sustainability. Its Presidency has translated that slogan into operational traction.
The recent BRICS Finance Ministers and Central Bank Governors meeting in Jaipur in mid-August prioritised financial stability, cross-border payments, financial technology collaboration, and private capital mobilisation. Trade Ministers followed, emphasising trade finance, digital services, and resilient value chains.
The $13bn inflow proves that an open and regulated approach to foreign stakes in banking and financial technology attracts substantial long-term capital while building local technological capacity.
The UAE's prominent role is particularly instructive. As a BRICS member since 2024, the Emirates have deployed billions into Indian financial institutions, strengthening corridors that align with the bloc's payment systems and local currency settlement agendas.
For African economies, this is a replicable template. South Africa, Egypt, and Ethiopia now provide seats at the BRICS table. Gulf states have deep trade and investment ties across East and West Africa. If the UAE capital can anchor Indian retail banking through RBL Bank, why can similar structures not be built with South African, Senegalese, Kenyan, or Nigerian partners?
With these nations now full BRICS members and several other African nations in the partner country pipeline, the continent now has the diplomatic heft to negotiate such arrangements on equal footing.
The New Development Bank (NDB) remains Africa’s most tangible BRICS asset. Earlier this year, the NDB approved a $1bn loan for South African municipal infrastructure, a welcome but modest start against the continent’s estimated $100bn+ annual infrastructure gap.
Africa is not arriving empty-handed. The African Continental Free Trade Area (AfCFTA) provides the same continental-scale market that India leverages domestically, a $3.4 trillion economic space with 1.4 billion people. More critically, the Pan-African Payment and Settlement System (PAPSS) already offers a live, operational platform for cross-border local-currency transactions.
Here lies the strategic opportunity: India and BRICS are actively exploring digital payment interoperability and local-currency settlement mechanisms. African institutions should use the New Delhi summit to formally propose a technical bridge between PAPSS and the BRICS Cross-Border Payments Initiative (BCBPI).
Such a linkage would slash transaction costs, reduce dollar dependency for intra-African and Africa-BRICS trade, and accelerate financial integration, without waiting for Western-led reforms.
With India at the helm, African members should push for a dedicated Africa infrastructure facility within the National Development Bank (NDB) that mirrors India’s openness to co-financing with private capital from BRICS member states.
India’s experience proves that regulatory predictability and strategic openness can crowd in not just multilateral dollars but also private equity, sovereign wealth funds, and corporate stakes. African regulators should study India’s foreign investment caps, licensing frameworks, diplomatic prowess and fintech sandboxes, not to copy blindly, but to adapt to local realities.
With the summit on the horizon, the window is narrow but actionable. African finance ministries, central banks, and the BRICS Business Council’s African chapters must finalise concrete proposals for side meetings.
Priority deliverables should include:
- A joint working group on BRICS-Africa fintech interoperability, with clear timelines for connecting PAPSS to BRICS payment rails.
- A private-capital mobilisation framework that encourages BRICS-based banks and investment firms to take anchor stakes in African financial institutions, using the India-UAE deals as a benchmark.
- An NDB co-financing facility that blends development finance with commercial capital for African infrastructure, digital identity, political will, and trade logistics projects.
For the Global South, India’s banking boom is not merely a domestic success story; it is a strategic signal. It shows that when BRICS members align regulatory openness, diplomatic will, and market scale, billions flow across borders within the bloc.
Africa sits at the intersection of all three. The AfCFTA provides scale. PAPSS provides payments infrastructure. And the NDB provides the institutional vehicle.
The question for African leaders in New Delhi is not whether BRICS cooperation matters; the $13bn answer is already clear. The question is whether they will leave with binding mechanisms to ensure Africa’s share of that capital tide rises as swiftly as India’s has.
Phapano Phasha is the chairperson of The Centre for Alternative Political and Economic Thought.
IOL